Total Compensation: The Number Recruiters Use to Make Less Money Look Like More
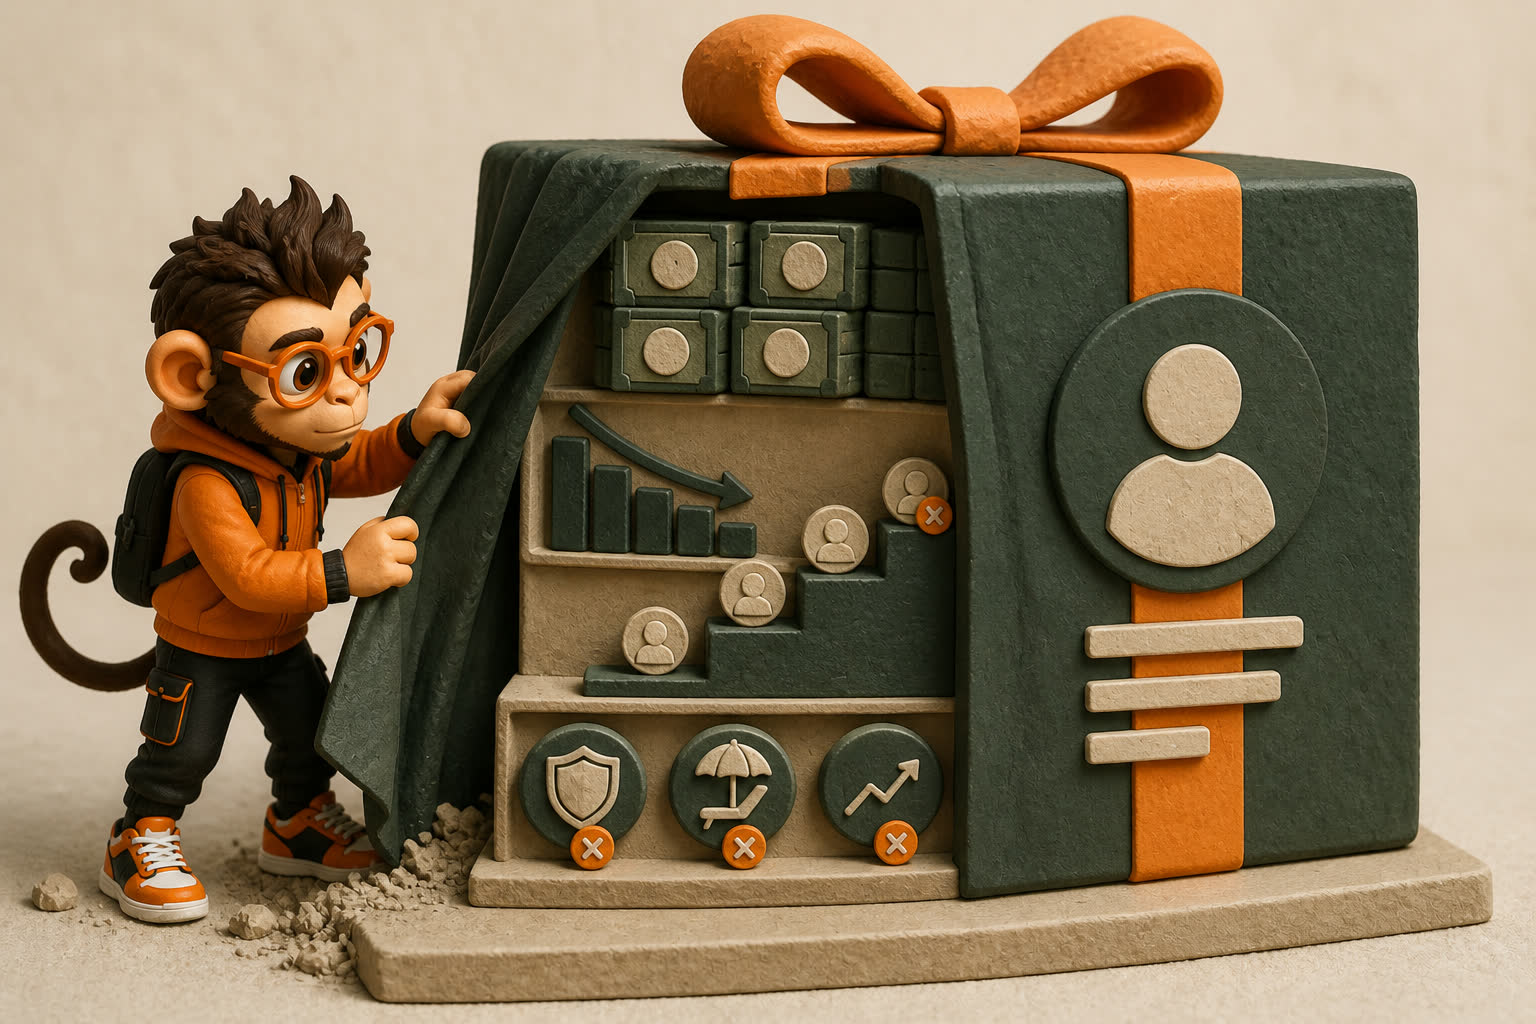
Total compensation is your base salary plus everything stacked on top of it: the equity grant spread over its vesting years, the target bonus, and the signing bonus amortized into a yearly figure. Only one of those lines is guaranteed, and it's the only one that compounds: your base. Everything else is contingent on you staying, performing, and a stock price the recruiter can't promise. The "total comp" number is the sum of those contingencies dressed up as cash.
Here's the formula recruiters use, laid out the way Levels.fyi defines it:
Total comp = base salary + (equity grant ÷ years to vest) + annual target bonus + (signing bonus ÷ years to vest)
And here's what each term is actually worth to you:
- Base salary: guaranteed, paid every month, and the anchor for raises, your next offer, and a mortgage application.
- Equity: paid only as it vests, usually over four years with a one-year cliff, at a price nobody can promise.
- Target bonus: a performance-gated range that can land below target or at zero.
- Signing bonus: one-time cash, often clawed back if you leave early, quoted as if it recurs.
Here's what most people get wrong. They treat the big total-comp figure as the offer and the base as a detail. It's backwards. The recruiter quotes total comp precisely because it's the number they can inflate without spending a dollar more in guaranteed pay. The base is what they actually committed to. The rest is a forecast you're being asked to mistake for a deposit.
Base salary vs total compensation: which number is real?
Base is real. Total comp is an estimate, and a generous one.
The catch is that you often don't even get to see the real number until you're deep in the process. In a June 2026 snapshot of 53,802 active postings from Praxy's job index, only about 9% (roughly 4,787) disclosed any pay figure at all. The single line that compounds, that anchors your next offer, that a bank underwrites your mortgage against, is the one employers are least willing to put in writing up front. The total-comp framing fills that vacuum, and it fills it in the company's favor.
Start with what "total comp" is even made of. Levels.fyi spells out the formula: base salary, plus the equity grant divided by the years it takes to vest (usually four), plus annualized bonuses, including a signing bonus spread across that same four-year vest. In their worked example, an L4 engineer's headline $250K total comp is base $150K, a $300K equity grant shown as $75K a year, and a 15% target bonus of roughly $22.5K. Do the math on that: about 40% of the glossy number is unvested equity you only receive if you stay the entire schedule.
Now look at how the rest of the economy is actually paid. For private-industry workers in March 2025, wages and salaries were $31.89 an hour, or 70.3% of total compensation, while nonproduction bonuses cost employers just $1.36 an hour, a 3.0% sliver. Even bundling overtime and shift differentials in, total supplemental pay is 4.2%. The number that dominates compensation across the labor market isn't the variable line. It's the base. The tech offer that flips that ratio, where 40% of the quote is contingent, is the anomaly, not the norm, and it's an anomaly engineered to make a smaller guaranteed number look bigger.
Why does the equity in the quote rarely fully arrive?
Because you leave before it vests. Not because you're flaky. Because that's what a normal career looks like.
The standard grant vests over four years with a one-year cliff. The median U.S. worker's tenure with their current employer was 4.1 years in January 2026, and just 3.0 years for workers ages 25 to 34. Hold those numbers next to each other. A standard grant runs about as long as the typical worker's entire tenure, and a full year longer than the median for 25-to-34-year-olds. Plenty of people leave before a standard grant fully vests, forfeiting the back-loaded shares that did the most to inflate the original total-comp quote. If you leave after two years, which plenty of people in fast-moving tech teams do, the haircut is brutal: you collect half the equity the recruiter counted, and you walked away from the rest.
This isn't a fringe risk you can plan around with willpower. It's the base rate. The recruiter quoted you four years of equity knowing the typical hire collects a fraction of it. The grant is structured as a retention trap, not a payout, and the cliff is the teeth. The "total comp" math assumes the outcome the data says is a coin flip at best: that you stay for the full ride.
And that's before the stock price moves. Levels.fyi values your grant at today's price. Private-company equity is valued at a number set by the last funding round, which can be marked down to zero. The equity line is a lottery ticket priced as if it were salary, and the ticket is printed into your offer at face value.
Is the target bonus a number you'll actually be paid?
No. It's a ceiling-and-floor range with your name written near the top of it, in pencil.
In WorldatWork's 2025 Incentive Pay Practices survey, 90% of publicly traded companies run an Annual Incentive Plan, and these plans are explicitly at-risk and leveraged. Organizations set separate threshold, target, and maximum payout levels, which means the actual bonus can land anywhere from a fraction of target down to zero. 99% pay out in cash, 83% pay once a year. The "target bonus" in your offer letter is the middle of a performance-gated range, not a commitment. You hit it in a good year for the company, miss it in a bad one, and the company decides which kind of year it was.
How big is that swing in dollars? Smaller than the framing implies. A typical bonus benchmark runs about 9.6% of salary across industries, with technology and software typically at 10 to 20% of base. Even at the high tech end, the at-risk bonus is a fraction of base, and it's the fraction most likely to evaporate. Bundling a conditional 15% into your headline number, then quoting it as if it's guaranteed, is the cleanest trick in the deck. Treat the target bonus as marketing until it clears your account.
What does the offer actually look like when you price what's guaranteed?
Here's a single offer, valued two ways. Same paper. Different question.
| Component | As quoted ("total comp") | What's actually guaranteed in year one |
|---|---|---|
| Base salary | $150,000 | $150,000 (the only line that compounds into raises) |
| Equity ($300K / 4-yr vest) | $75,000/yr | $0 until the 1-yr cliff; ~$37.5K if you reach year two |
| Target bonus (15%) | $22,500 | A threshold-to-max range, often below target, sometimes $0 |
| Signing bonus ($40K) | ~$10,000/yr (amortized) | One-time, frequently clawed back if you leave early |
| Headline | ~$257,500 | $150,000 hard, the rest forecast |
The quoted number is real arithmetic. It's just answering the wrong question. "Total comp" tells you the maximum you could earn if you stay four years, the company performs, and the stock holds. The guaranteed column tells you what you can count on to pay rent, qualify for a mortgage, and anchor your next negotiation. When you compare two offers, compare the guaranteed columns first. A job that quotes $257K against a base of $150K can pay you less, in cash you actually keep, than a job that quotes $210K against a base of $185K.
Why does this framing work so well on candidates?
Because it hits exactly where people are most anxious and least rational about money.
Pay is the single most contested part of the employment relationship. Only 30% of U.S. workers are extremely or very satisfied with how much they're paid, against 50% who are satisfied with the job overall. Among the dissatisfied, 80% say pay hasn't kept up with cost of living. A bigger-looking number lands hardest on the people most worried they're underpaid, which is most people.
And there's a deeper hook. A 2024-25 study of job seekers found the marginal value of pay is 12% higher for pay cuts than for equivalent raises, with job changes clustering at exactly zero wage growth at 8.5x the rate a loss-aversion-free model predicts. Translation: you anchor hard on your current base and treat any drop as a loss you'll do almost anything to avoid. That's the exact reflex a glossy total-comp figure is built to exploit. The recruiter knows a base below your current base reads as a pay cut and kills the deal. So they show you a total-comp number above your current total, which lets a lower guaranteed base slip past your loss alarm. The number isn't lying. It's aiming at the part of you that confuses "bigger headline" with "more money."
When is the equity worth a lower base? (the part nobody mentions)
Here's where the contrarian take owes you honesty. Pricing only the guaranteed column is the right default, and it's wrong for some people.
If you're joining a company you genuinely believe will be worth far more in four years, the equity isn't padding, it's the entire reason to take a lower base. Early employees at companies that actually made it didn't get rich on salary. They got rich on the contingent line everyone else is told to discount. Loss aversion cuts both ways: anchoring so hard on guaranteed cash that you never take an equity bet can be its own expensive mistake. The discipline isn't "ignore equity." It's "price equity as the risk-adjusted bet it is, then decide on purpose."
Two honest caveats on that bet. First, your conviction needs to survive the question "would I buy this stock with cash at this valuation?" If the answer is no, the grant isn't a reason to accept a pay cut. Second, the guaranteed base still sets the floor under everything: your raises compound off it, your next offer anchors off it, your loan applications run off it. Taking a low base for big equity is a real strategy. Taking a low base because the total-comp number felt big is not a strategy. It's the trick working.
Weak version (accepting the quote): "The recruiter said it's $257K total, which is up from my $230K, so this is a raise. I'll take it."
Strong version (pricing the guarantee): "Your guaranteed base is $150K against my current $185K, so on cash I can count on, this is a 19% pay cut that the equity and target bonus only cover if I stay four years and a few things break right. Either move the base to $175K, or tell me why the equity is worth betting $35K of guaranteed annual pay on, because right now the headline is doing work the numbers don't support."
The strong version doesn't reject the equity. It refuses to let the equity be quoted as cash. That single move, separating what's guaranteed from what's forecast, is the entire negotiation.
What to do now
- Split every offer into two columns: guaranteed and contingent. Base goes in guaranteed. Equity, target bonus, and amortized signing bonus go in contingent. Compare offers on the guaranteed column first, every time.
- Ask the recruiter to state the base separately, out loud. "What's the base, before equity and bonus?" If they keep steering back to total comp, that's the tell. The number they avoid is the number that matters.
- Discount the equity to what you'll realistically vest. Use the 3.0-year median tenure for workers ages 25 to 34 if that's your bracket, or your honest guess at how long you'll stay, not the full four-year grant. Then decide if the bet is worth the lower base.
- Negotiate the base first, the rest second. Base is the only line that compounds into raises and follows you to your next offer. A dollar of base outvalues a dollar of target bonus or a dollar of unvested equity, because it's the only one you're guaranteed to keep. Read where comp actually dies on the refresh before you sign for the grant.
- Treat a "lower base, bigger total comp" offer as a pay cut until proven otherwise. Make the company prove the contingent lines are worth it. The burden is theirs, not yours.
Got an offer with a big total-comp number and a base you're not sure about? Send me both columns on WhatsApp. I'll help you price what's actually guaranteed, value the equity as the bet it really is, and write the line that gets the base moved before you sign.
Related reading
RSU Vesting: Your Vesting Schedule Isn't a Gift. It's a Leash.
RSU vesting, explained: 50,000 workers walked from $1.8B in vested equity in 2022. The cliff and four-year grant aren't generosity, they're a leash.
Being the "Strong Number Two" Is a Real Position. Play It Like One.
Being the runner up job candidate isn't the end. One in three accepted offers fall through, and recruiters call the shortlist first. Here's how to be that call.
Nobody Negotiates the Refresh, and That's Where Your Comp Dies
Your equity refresh grant decides comp for years 5 to 15, not the initial RSU. Why year-five pay drops 30-50%, and the 5 questions to ask before signing.
Startup Equity: A Lottery Ticket the Company Prices Like Cash
65% of venture financings fail to return 1x. Is startup equity worth it? The real math on preferences, dilution and time, and what to negotiate first.