Is Consulting a Good Career? It's a Bet on Exit Options, Not a Career
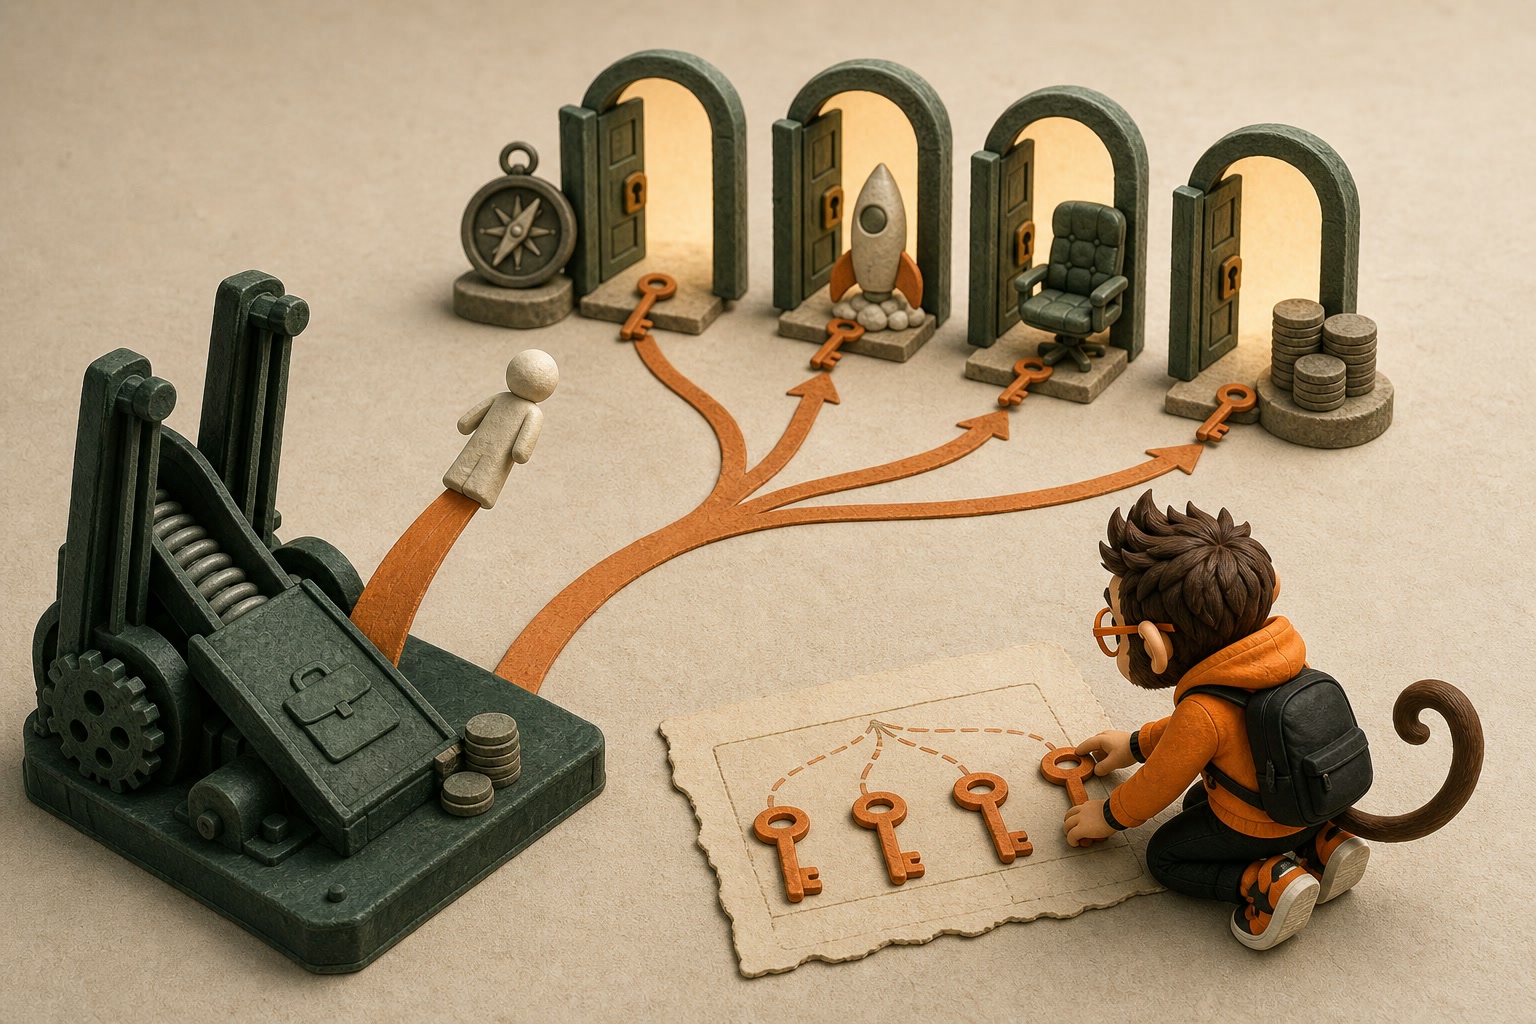
Is consulting a good career? For most people, no, and that's fine, because it's a very good two-year bet. Consulting (and investment banking, which runs on the same model) is a short stint that buys a credential and a network, paid for in hours and health. Here's the trade at a glance:
| What the stint buys | What it costs |
|---|---|
| Access to private equity and the buy-side, with recruiting that starts in an analyst's first year | Weeks that averaged 77.73 hours in a survey of 485 bankers |
| A file that top MBA programs take seriously | Self-rated mental health down from 8.0 to 5.6 out of 10 in that same survey |
| A founder and operator network: 6.3% of MBB leavers go on to found companies | 75% saying the hours damaged their relationships |
| A clean exit after the typical two to four years of analyst tenure | Only a small fraction ever make partner |
You're not joining McKinsey or Goldman to build a career there. Almost nobody does, and the firms know it. 88% of consultants join as a means to an end, not a lifelong calling. You're buying a credential and a network that open specific doors later. The job is the packaging. The exit is the product.
That's not cynical. It's the honest read, and it's the one almost nobody says out loud. The mistake people make isn't taking the bet. It's taking it without naming what they're buying, so when they burn out around month 20, they default to whatever exit is easiest to fall into instead of the one they actually wanted.
Is consulting a good career, or just a good two-year bet?
It's a good two-year bet for most of the people who take it, and a good 30-year career for very few. Those are different questions, and conflating them is where people get hurt.
The structure tells you everything. Up-or-out means the pyramid is designed to spit most people out. Analyst tenure at MBB runs about two to four years before they leave, with most departures clustering in that window. That's not a wave of quitting. That's the model working as intended. The firm hires far more analysts than it will ever need as partners, runs them hard, and counts on attrition.
So when you ask "is this a good career," you're asking the wrong question for the situation you're actually in. The right question is: is this a good position to hold for two to three years, given what I want next? For a large share of ambitious people, the answer is yes. Just be honest that you're buying optionality, not a home, and that committing to it as a forever plan is the same mistake as treating any five-year plan as a contract instead of a working hypothesis.
What does the credential actually buy you?
A brand on your resume that gets you into rooms you couldn't otherwise enter. That's it, and it's worth a lot. It opens three specific markets.
Private equity and the buy-side. Banking is still the dominant feeder. The recruiting is so aggressive it's almost comic: megafund on-cycle recruiting now kicks off in an analyst's first year, often before they've closed a single deal. You're being evaluated as an option before you've done the underlying work. The exit-option framing isn't a metaphor here. It's the literal mechanic.
Top MBA admissions. The MBB or bulge-bracket stamp gets your file taken seriously at HBS, GSB, and Wharton. It signals you survived a filter, which is most of what the brand sells. (Whether the MBA itself pays back is a breakeven worth running before you apply.)
Startups and the operator track. The network compounds well past the stint. By the count of Marvin Ventures, as reported on McKinsey's alumni site, about 1 in 12 McKinsey alumni-founded startups has reached unicorn status, with an estimated post-seed failure rate around 15% against 80 to 90% for the broader market. That's an alumni-affiliated analysis, not an independent one, so hold it loosely. The brand doesn't just open doors to jobs. It opens doors to capital, recruiting, and enterprise sales. In the 2025 data, 6.3% of MBB leavers went founder and 30.6% landed at companies with $25M or less in revenue.
Where the exits actually go tells the story plainly:
| Exit destination | Share of MBB departures |
|---|---|
| Business consulting (another firm) | 16.6% |
| Financial services | 13.7% |
| Software development | 13.1% |
| Founder | 6.3% |
| VC and PE | 5.1% |
What does the bet actually cost?
Two to three years of your health, your relationships, and your time. Don't let anyone sanitize this, including yourself.
The numbers are ugly and consistent. A 2022 survey of 485 investment bankers put the average at 77.73 hours a week, with 14% over 91 hours. Self-rated mental health fell from 8.0 to 5.6 on a 10-point scale. Physical health fell from 8.1 to 5.1. 75% said the hours damaged their personal relationships, and 25% felt they'd been victims of workplace abuse. The 2024 follow-up didn't improve much: 62% reported relationship damage, mental health down 22%, physical health down 26%.
The burnout is doing real things to retention. A report on 200-plus finance professionals found 72% considering quitting to avoid burnout and 76% who'd take a lower salary for better work-life balance. Read that twice. Three in four would trade money for their life back.
And the most telling artifact of all: in 2021, 13 first-year Goldman analysts built a pitch book to present their own working conditions to management. They reported 95-hour average weeks, one week peaking at 108, health scores down more than 6 points, and 77% feeling subjected to workplace abuse. Even the protest had to be packaged in the firm's house format. That's the price of the option. It's a real price, the kind that turns these stints into prestige jobs you effectively pay the company to hold. Naming it is the difference between a clear-eyed bet and a hopeful one.
What does this look like done well versus done badly?
The decision is identical. The difference is whether you said it out loud.
Weak. "I joined McKinsey to learn about business and build a career."
Strong. "I joined McKinsey with a 24-month PE recruiting timeline already mapped, the specific sector expertise I needed to build, and two partners I planned to line up as references."
Same firm, same two years. The second person has an exit thesis. She knows which of the three markets she's buying access to, which means she can steer her staffing toward the projects that build it and the relationships that vouch for it. The first person is hoping the brand carries him somewhere good. It might. But he's a passenger.
Consistency beats intensity here too. The person who quietly builds one coherent story across two years (one sector, one type of problem, one set of advocates) exits stronger than the person who grinds 90-hour weeks on whatever lands on their desk. The hours feel like progress. The story is the progress.
Where does the strategy break down?
Three failure modes, and they're predictable.
You never name the exit, so you default into one. The path of least resistance in banking is PE, because the recruiting comes to you on a timer. Plenty of people end up in PE for one reason only: it was the easiest door open at month 14. A default is not a decision.
You stay one year too long. The marginal brand value peaks around year two or three. After that, an extra year in the same analyst seat adds real cost (opportunity, health, the relationship you keep postponing) without proportional credential gain. The option has an expiry. Treat it like one.
You bet on the brand alone. The brand opens the door. It doesn't close the deal. Of 47 Fortune 500 CEOs with top-tier consulting backgrounds, exactly zero went straight from consulting to CEO, and only three jumped directly into any C-suite role. McKinsey alone produced 17 of those 47, so the pipeline is real. But every one of them went and got operating experience first, eating the temporary pay cut that any real pivot carries on the way to the operating role. The credential is the down payment. The operating years are the mortgage.
Is the consulting exit window narrowing, and do some people stay?
Both true, and both matter to how you size the bet.
Some people stay, and for the small fraction who make partner it's a genuine wealth path. That's a real career, not a stepping stone. If you're aiming there, you're playing a different game than the optionality buyer, and you should know which game you're in.
The prestige is also softening at the top of the funnel. For the MBA Class of 2024, consulting placements hit five-year lows at 22 of 24 tracked programs, with M7 schools down 4 to 12% year over year. And on the banking side, PE on-cycle participation among elite analysts slipped from 72% to 59%. The exits people assume are automatic are getting more contested. If you're buying the option, buy it knowing the premium may be shrinking in mature markets.
The flip side, and here our read is that the picture looks different: in India and parts of Southeast Asia, the consulting brand still feels closer to the front of its premium cycle than the back, with firms hiring and the stamp carrying outsized weight. For a candidate there, the same two-year bet may buy a larger option premium than for a US counterpart. The thesis holds. The price just varies by market.
What to do now
Name your exit thesis before you start, or as early as you can if you're already in.
- Pick one primary market. Buy-side, MBA, or operator/founder. Write it down; a default is not a decision.
- List what the stint must produce. Which sectors, which kinds of projects, and which two or three people will vouch for you when you leave.
- Steer your staffing toward that list. Ask for the projects that build the story, and decline the ones that only fill hours.
- Set an expiry date. Decide now what would make you leave a year early rather than a year late, because the brand value peaks around year two or three.
- Price the cost honestly. If the hours are already costing your health or a relationship you care about, count that in the bet, not after it.
If you can answer those, you're making the bet with your eyes open, and it's often a good one. If you can't, you're paying the full price of the option without knowing what you're buying. That's the only real mistake here.
Six months into a stint and still can't name your exit thesis? Message Praxy on WhatsApp. We'll map which exit you're actually optimizing for and reverse-engineer what these two years need to produce, so you leave on your terms instead of scrambling for a door at month 20.
Related reading
The 40-Year Career at One Company Is Gone. Stop Mourning It.
Average job tenure in 2026 sits near four years, not forty. Here's what actually changed, who moved the risk onto you, and what to build instead.
Is an MBA Worth It? Run Your Breakeven Before You Apply
Is an MBA worth it? A top US program costs about $500K all-in once lost salary counts. Here's who it pays for, by school tier, target field and market.
Prestige Is a Salary You Pay the Company, Not One They Pay You
Prestige vs pay: why dream jobs underpay by design, what the discount really costs over a career, and three questions to ask before you take one.
The Five-Year Plan Is a Liability Dressed as Maturity
Why the five year career plan locks you into a guess your past self made with worse data, and what to set instead so every move stays reversible.